
Life Insurance for Every Stage of Life
Final Expense Term Life Mortgage Protection
Rate example
Burial Insurance
$15,000 , Moderate Health
$47.61
/month Example rates. Your rate may vary.
Rate example
Burial Insurance
$10,000 , Average Health
$32.78
/month Example rates. Your rate may vary.
Rate example
Mortgage Protection
$250,000 , 15-Year
$57.60
/month Example rates. Your rate may vary.
Rate example
Mortgage Protection
$350,000 , 15-Year
$52.98
/month Example rates. Your rate may vary.
Rate example
Term Life Insurance
$1,000,000 , 20-Year
$68.26
/month Example rates. Your rate may vary.
Rate example
Term Life Insurance
$500,000 , 20-Year
$34.13
/month Example rates. Your rate may vary.
One Agent. Multiple Companies. More Options.
Independent Broker
Randy can compare options from multiple insurance companies instead of selling just one.
No Call Center
You deal directly with Randy, not a call center.
First-Day Coverage
Plans are built to qualify you for first-day coverage whenever possible… not default you into expensive waiting-period plans.
Licensed in Most States
Call Randy to find out what options are available in your state.
What Does Final Expense Life Insurance Cover?
Final expense life insurance covers any financial responsibility you’ll leave behind after your death. That includes paying off your home mortgage, car loans, credit cards, funeral bills, your kids’ education, everyday living expenses, or providing ongoing financial security for your family or business.
What I Help People With
Real Customer Experiences
476Customer Reviews
Read what Final Expense Guy customers have to say about working with Randy.
READ ALL 476 CUSTOMER REVIEWS“Randy found a whole life policy for me that has immediate coverage. No waiting period. The price was right for the coverage amount.”
Glenda P. - Auburn, GA “Randy was very informative and patient with getting me approved for life insurance when no other agent could. I like that I can access accelerated death benefit payment, and low monthly payment.”
Danielle N. - Kansas City, MO “Randy was a blessing. He saved us money, and he was very truthful and easy to talk to. He was great. Price was great and easy to apply. Thanks so much.”
Dolores W. - Frederick, MD
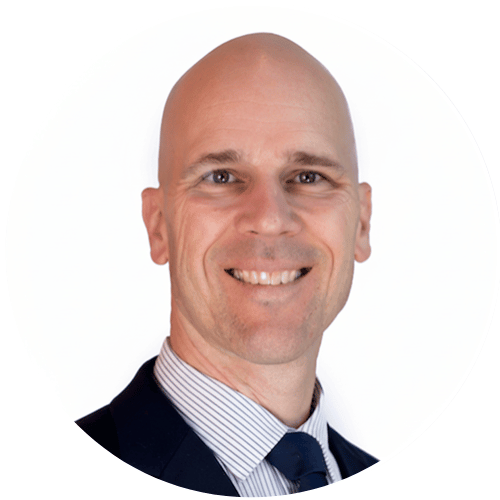
Meet Randy
Final Expense Guy isn’t a call center. When you call, you deal directly with Randy.
Randy is an independent life insurance broker, licensed in most states. Because he isn’t tied to one insurance company, he can compare options from multiple companies to help you find the right fit.
You won’t be handed off from one representative to the next. You’ll talk with Randy.
Health Problems Don’t Always Mean No
Research Life Insurance Companies Before You Buy
Life Insurance Resources
- Burial Insurance Learn how burial insurance works, what it costs, and how to find the right coverage.
- Mortgage Protection Life Insurance How mortgage protection works, how much coverage you need and for how long, and whether term, whole life or final expense fits best.
- Term Life Insurance How term life works, choosing a term length, how much coverage families usually need, and how pricing and medical underwriting affect your rate.
Frequently Asked Questions
Short answers to common questions about life insurance. For answers about your own situation, call Randy at 888-862-9456.
What’s the difference between final expense, term life and mortgage protection insurance?
Final expense insurance, often called burial insurance, is a small whole life policy that helps your family pay for a funeral and other final expenses. It lasts for life as long as you pay the premiums. Term life insurance covers you for a set number of years, such as 10, 20 or 30, and usually costs the least per dollar of coverage, which makes it a common way to replace your income while your family depends on it. Mortgage protection is mainly a reason for buying life insurance rather than a separate type: a policy, often term life, with enough coverage for the right length of time so your family can pay off the mortgage or keep making the payments.
How much life insurance do I need?
It depends on what you want the money to cover. Start with funeral, burial or cremation costs, then add your mortgage balance, other debts such as car loans, credit cards and medical bills, and any income your family relies on. Final expense coverage usually focuses on the funeral and final bills, while term life and mortgage protection are usually sized to pay off a home or replace income. There’s no single right number; it depends on your family’s needs.
Can I get life insurance if I have health problems?
In many cases, yes. Each insurance company looks at health conditions differently, so a condition that leads to a decline at one company may be accepted by another. For term life, conditions such as high blood pressure, diabetes and heart problems can raise the premium, shorten the term lengths available or limit the coverage amount. For final expense, many common conditions can still qualify for first-day coverage, while more serious or recent conditions may limit the types of coverage available.
Do I need a medical exam?
Often not. Most final expense plans ask health questions instead of requiring a medical exam, and the insurance company may also check your prescription history. Some term life applicants can skip the exam through accelerated underwriting or nonmedical programs; nonmedical programs often have stricter health rules and lower coverage limits, and other applicants may still need an exam. Guaranteed-acceptance plans skip the health questions too, but they come with a two-year waiting period for death from natural causes.
Can my premium go up?
It depends on the policy. With a level-premium whole life or final expense policy, the monthly payment is set when the policy starts and doesn’t rise as you get older. With level term life, the premium stays the same for the term you choose; if you renew after the term ends, the price usually goes up, sometimes sharply. Some policies are built with increasing prices, so it’s worth checking before you buy.
What’s the difference between first-day coverage and a two-year waiting period?
With first-day coverage, the full death benefit is available as soon as the policy is approved and in force. With a two-year waiting period, if you die from natural causes during the first two years, your beneficiary generally receives the premiums you paid plus interest instead of the full benefit. Which one you qualify for depends on your answers to the health questions and the company you apply with.
Not Sure What Type of Life Insurance You Need?
Randy can help you compare your options.
CALL 888-862-9456