Quick Answer
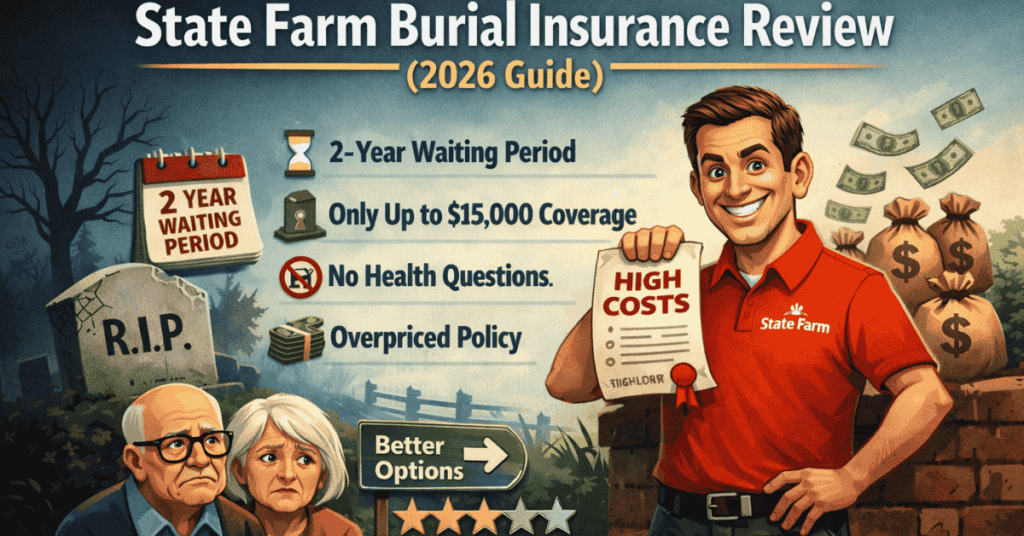
State Farm’s burial insurance is a guaranteed issue whole life policy, so there are no health questions or medical exam, but everyone faces a mandatory two-year waiting period. If you die of natural causes in the first two years, your family gets only the premiums paid plus 10% interest. Coverage tops out at $15,000 in most states, and pricing is higher because every applicant is treated as high-risk. If your health is stable, a policy with simple health questions can often give you first-day coverage for a much lower monthly cost.
Here’s What This Means for You:
- Mandatory two-year waiting periods apply to everyone who buys this policy, regardless of their actual health. I avoid this by checking your health history against carriers that offer immediate coverage, so your family is not left 100% unprotected for a full two years.
- Captive agents only sell State Farm products, which means they cannot offer you a better deal from a competing company, even if you qualify for it. I avoid this by acting as an independent broker who shops dozens of companies to find you the lowest price.
- Coverage limits are tiny, maxing out at only $15,000, which may not cover a modern funeral and final debts. I avoid this by using carriers that offer permanent whole life protection up to $25,000 or $50,000.
- Pricing is massively higher because State Farm assumes every applicant is at death’s door and wants to skip any health questions. I avoid this by using simplified underwriting that rewards your stable health with much lower monthly premiums and 1st-day coverage.
- Guaranteed worst-in-class pricing in most cases. So you pay a massive amount of money just for the privilege of skipping health questions you’d have likely passed anyway. I avoid this by using a quick background check on your prescriptions to find 1st-day coverage that can often cut your monthly bill in half compared to State Farm’s rates.
GET MY QUOTEor call 888-862-9456
NOTE: Burial, cremation, funeral, and whole life insurance are all types of final expense life insurance.
Most people can get easy approval for 1st-day coverage with great companies through my simple process, which handles the hard work for your family.
Expert 5-star burial insurance rating
★☆☆☆☆ Lowest Prices
★☆☆☆☆ First-Day Coverage
★☆☆☆☆ Burial Insurance Suitability
★★★★★★ Underwriting Flexibility (guaranteed issue)
State Farm burial insurance basics
State Farm operates as a massive captive agency force that primarily focuses on home and auto insurance rather than specialized final expense products. This specific burial or final expense life insurance policy is a guaranteed acceptance whole life plan with a MANDATORY waiting period. It simply doesn’t make sense to buy a policy with a MANDATORY 2-year waiting period if you are healthy enough to get 1st-day coverage starting today.
State Farm underwriting & eligibility
State Farm uses guaranteed issue underwriting to determine applicant eligibility, eliminating health questions and medical exams. State Farm does not check the Medical Information Bureau (MIB) or prescription databases for this specific plan. Because they accept applicants with the most serious health problems, they must treat everyone as an ultra-high risk. This type of policy forces all policyholders to pay higher prices and face a two-year waiting period, even when their health is otherwise stable.
Do you remember those commercials that say, “Like a good neighbor, State Farm is there”?
For this policy, they need to change that to “Like a good neighbor, we’ll stick you with an overpriced two-year waiting period policy when you could actually qualify for first-day coverage.” If you can walk and talk, you can probably qualify for something better than a guaranteed issue plan. Most of the people I help are shocked to find they can get immediate coverage elsewhere for up to half the price State Farm charges.
State Farm policy types & waiting periods
Waiting periods apply to guaranteed-issue policies to offset the risk of high mortality, which means your family gets nothing but a refund if you die in the first 24 months. State Farm offers only one plan type in this category, a modified benefit whole life policy that strictly limits your natural death coverage. If you pass away from natural causes in Year 1 or Year 2, your family will receive only the premiums you paid, plus 10% interest.
Understanding State Farm policy types
State Farm skips standard coverage tiers like first-day or graded plans and defaults every applicant to a guaranteed issue policy.
- Level: Level burial insurance offers 1st-day coverage and pays the full death benefit from day one, but State Farm does not offer this plan for its final expense product.
- Graded: Graded burial insurance limits benefits during the 12 to 24 months for health-related causes of death, but State Farm skips this middle-ground option entirely.
- Guaranteed Issue: Guaranteed issue burial insurance requires no health questions but includes a 2-year waiting period before it pays out for causes of death related to health or medical conditions. Sadly, this is the type of plan that State Farm is offering here.
| Year of Policy | Natural Cause Payout | Accidental Cause Payout |
|---|---|---|
| Year 1 | Premiums + 10% Interest | 100% Death Benefit |
| Year 2 | Premiums + 10% Interest | 100% Death Benefit |
| Year 3+ | 100% Death Benefit | 100% Death Benefit |
State Farm rate analysis
State Farm lacks an underwriting process for its guaranteed issue product, leading to higher assumed mortality rates and inflated monthly premiums for every policyholder. Because this specific plan uses a “one size fits all” pricing model, a healthy 60-year-old pays the exact same high rate as someone currently in hospice care. This makes the policy a terrible deal for anyone who isn’t terminally ill.
Sample State Farm monthly rates ($10,000 coverage)
| Age | Male Monthly Premium | Female Monthly Premium |
|---|---|---|
| Age 60 | $82.50 | $61.40 |
| Age 65 | $104.20 | $76.80 |
| Age 70 | $135.90 | $102.10 |
State Farm agents skip all health questions for this plan, which means every client faces a mandatory two-year waiting period for natural causes of death. Because the company treats every applicant as high-risk, a healthy senior ends up paying the same inflated monthly rates as someone with a terminal illness.
The long-term value of two-year waiting period plans is extremely low. If you overpay by $61.25 per month, that is $735 per year and $7,350 over 10 years. On a $10,000 policy, paying an extra $7,350 in premiums destroys the coverage’s value.
Even if the policy eventually pays out, a large portion of the benefit has already been spent on keeping the policy active.
State Farm financial strength & consumer trust
State Farm maintains a high A.M. Best rating, which reflects its massive capital reserves rather than the value of its burial insurance. While the company is financially stable enough to pay claims, the industry’s high complaint volume often stems from confusion about pricing and waiting periods. Most families are devastated to learn their “Good Neighbor” policy won’t pay for the funeral because the 24-month clock hasn’t run out yet.
| Feature | State Farm GIFE | Independent Level Plan |
|---|---|---|
| Waiting Period | 24 Months | 0 Months |
| Health Questions | None | Simplified |
| Monthly Cost | High | Low |
State Farm pros and cons
Comparing State Farm policy advantages and limitations helps seniors make informed decisions to protect their families.
PROS
- Financial Backing: State Farm is one of the wealthiest companies in the world.
- Fixed Premiums: Your higher price never changes, even as you get older.
- Local Agents: You can visit an office in person in almost any town.
CONS
- Terrrible Two-Year Wait: No natural death coverage for the first two years of the policy.
- Unnecessarily Overpriced: Rates are often double what healthy seniors should pay.
- Low Coverage Limits: You cannot buy more than $15,000 in coverage in most states.
State Farm shouldn’t even serve as a last-resort profile for people who have been declined by every other insurance company due to terminal illness. If you have been told by a State Farm agent that this is all you qualify for, then you should give me a call right away.
Frequently asked questions: State Farm burial insurance review
Does State Farm offer burial insurance?
State Farm provides a “Guaranteed Issue Final Expense” policy specifically designed to help families cover funeral and end-of-life costs. This plan is a whole life insurance contract, meaning the premiums are locked in for life, and the coverage will never expire as long as payments are made. Because it is “guaranteed issue,” State Farm does not require a medical exam or ask any health questions during the application process.
Is State Farm burial insurance a good deal for seniors?
State Farm’s final expense plan is generally more expensive than “level benefit” plans because the company accepts applicants with terminal illnesses. Since the insurer takes on much higher risk by skipping health questions, they charge everyone a higher premium to compensate. Most seniors in 2026 find they can get the same amount of coverage for nearly half the price by choosing a company that asks a few basic health questions.
How does the State Farm two-year waiting period work?
The State Farm waiting period requires the policyholder to survive for 24 months before the full death benefit becomes payable for natural causes. If death occurs from natural causes (such as illness or old age) during these first two years, State Farm will refund only the premiums paid, plus 10% interest, to the beneficiaries. Full protection only kicks in on the first day of the third year, though accidental deaths are covered in full immediately.
What is State Farm’s reputation for paying life insurance claims?
State Farm holds one of the strongest reputations in the industry for financial stability and claims-paying ability. With an A++ rating from AM Best and high rankings in J.D. Power customer satisfaction studies, the company is highly reliable in fulfilling its contractual commitments. However, most consumer complaints regarding their burial insurance stem from families being surprised by the mandatory two-year waiting period at the time of a claim.
Can I get State Farm burial insurance with a heart condition?
State Farm will approve you for burial insurance regardless of your heart condition or medical history because the policy is guaranteed issue. Whether you have had a recent heart attack, congestive heart failure, or are currently on oxygen, you cannot be turned down. The downside is that you will be forced to wait the same two-year period as everyone else, whereas a specialized “high-risk” carrier might offer you coverage from day one.
Does State Farm burial insurance build cash value?
State Farm’s final expense policy accumulates guaranteed cash value that grows over the life of the contract. As you pay your monthly premiums, a small portion of that money builds up in a side account that you can access if needed. You may take out a loan against this cash value, though any unpaid loan amount will be deducted from the final death benefit payout sent to your family.
Who is eligible for State Farm final expense insurance?
Applicants must be between the ages of 45 and 80 to qualify for State Farm’s guaranteed issue burial plan (ages 50 to 75 in New York). This makes it a popular choice for older seniors who have been declined by traditional term or whole life insurance providers. Because there are no health questions, the only real requirements are meeting the age criteria and living in a state where the product is currently offered.
Why do some people say State Farm is overpriced?
State Farm is often considered overpriced for burial insurance because its “captive agents” only sell State Farm products and cannot shop the market for you. If you are a healthy 65-year-old, a State Farm agent will still sell you a “guaranteed issue” policy with high rates and a waiting period. An independent agent, by contrast, could find you a “preferred” plan that offers immediate coverage for a much lower monthly premium.
Is State Farm life insurance better than Colonial Penn?
State Farm is often viewed as a more stable alternative to the Colonial Penn $9.95 plan due to its superior financial ratings and local agent network. While both companies offer guaranteed acceptance plans with waiting periods, State Farm’s policy is a standard whole life contract with predictable pricing. Colonial Penn’s “unit” system can be confusing, often providing very limited coverage at the famous $9.95 price point as you get older.
What is the maximum coverage for State Farm burial insurance?
State Farm limits its guaranteed-issue final expense coverage to $15,000 in most states. This limit is lower than that of many other companies, such as Mutual of Omaha or Gerber Life, which may offer up to $25,000 or $40,000. For families needing a larger benefit to cover both a funeral and outstanding medical debts, State Farm’s small cap might not be sufficient.
What happens if I move to a different state with State Farm?
State Farm’s nationwide footprint ensures your burial insurance policy remains valid even if you move to a new state. Because they have local offices in nearly every town across the U.S., you can easily transfer your file to a local agent in your new neighborhood. The terms, premiums, and death benefit of your original contract will stay exactly the same regardless of your new address.